
Cashli: Cash Advance & Rewards
- Rating
- 4.1
- Downloads
- 100.00K
- Content Rating
- Everyone
Cashli: Cash Advance & Rewards - Screenshots
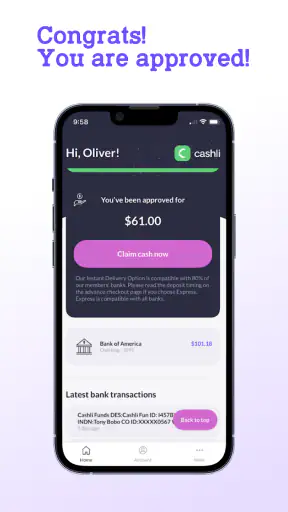
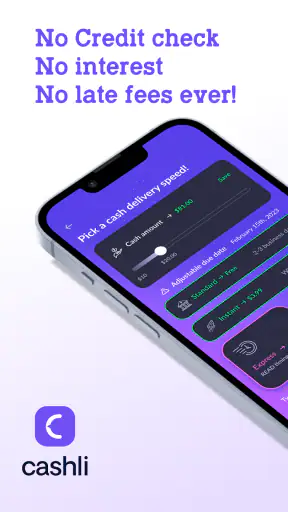
Pros
- Fast cash advances can help cover unexpected expenses between paychecks.
- Rewards give users extra ways to earn value beyond borrowing money.
- A mobile-first interface makes account access and requests convenient.
- Repayment details are shown clearly before accepting an advance.
- Useful option for users who may not qualify for traditional credit products.
Cons
- Cash advances may include membership
- transfer
- or other service fees.
- Borrowing can become expensive if advances are used repeatedly.
- Eligibility and advance limits may vary based on personal account activity.
- Repayment dates can create pressure when the next paycheck is limited.
- Availability and features may depend on location
- employer
- or banking setup.
Cashli: Cash Advance & Rewards - Description
- App Name
- Cashli: Cash Advance & Rewards
- Package Name
- com.wolfpackdigital.cashli
- Developer
- Cashli Funds
- Category
- Finance
- Last Updated
- Jul 18, 2023
- Version
- 1.0.19
When an unexpected expense lands between paydays, a small cash advance can sound more useful than another budgeting lecture. That is the space Cashli: Cash Advance & Rewards tries to occupy. I reviewed it as a finance app from Cashli Funds, focusing not only on the promise of getting money quickly, but also on the choices a user makes along the way, the information they may be asked to provide, and how clearly the app lets them stay in control.
My overall impression is cautious but practical. Cashli is free to install, rated for Everyone, and aimed at people who need a relatively small amount of short-term help rather than a long-term personal loan. Its store message presents access to up to 150 bucks, which immediately tells me what kind of product this is: something designed for a gap in everyday cash flow, not a replacement for savings or a full banking service.
The app has a 4.1 average from around 5 thousand ratings, with roughly 2.8 thousand written reviews and over 100 thousand installs. Those figures suggest that it has reached a meaningful audience, but they do not remove the need to read each offer carefully. In finance, popularity is not the same as suitability. I would still treat every screen involving eligibility, repayment, personal details, or account access as a decision point rather than tapping through automatically.
How Cashli fits into a real financial emergency
A narrow purpose rather than a complete money manager
Cashli makes the most sense when the amount needed is modest and the timing matters. Imagine a commuter whose paycheck arrives in a few days but whose car needs an urgent repair, or someone who has a small utility bill due before their regular income clears. In that situation, opening a focused cash-advance app may feel more direct than applying for a traditional loan or moving money around several credit accounts.
That convenience has a boundary. I would not use this kind of app to cover a recurring rent shortage, roll one advance into another, or solve a debt balance that has already become difficult to manage. A short-term advance can ease one specific timing problem, but repeated use can turn a temporary gap into a regular obligation. The right question is not simply whether Cashli can help today; it is whether repayment will still be comfortable when the next withdrawal or bill arrives.
The rewards angle also deserves a realistic interpretation. I would view rewards as an additional part of the experience, not as a reason to borrow. If the advance is unnecessary, the possibility of earning something inside the app should not change that decision. Borrowing for a reward reverses the sensible order of priorities.
What the first session feels like
The important part of the first session is not speed alone. It is understanding what Cashli is asking me to do before I reach a final request. I would begin by reading each permission prompt and account-connection screen separately. A request to use a financial account, verify identity, or assess eligibility can have a very different consequence from a simple notification request, so I would avoid approving a whole sequence without checking the wording.
I would also keep a record of the amount requested, any repayment date shown, and every fee or condition displayed before confirming. This is a simple habit, but it matters because a cash advance is easy to think of as “just a small amount.” The repayment obligation is the part that belongs in my budget, not the headline amount that appears at the start.
The current version is 1.0.19 and it supports Android 8.0 or later. That makes the app accessible to people using older Android phones, although compatibility alone does not tell me whether a particular device will offer the same flow or whether every screen will behave identically. I would keep the app updated through the official store and avoid installing modified copies that could interfere with account or payment security.
Trust starts with visible choices
For a finance app, trust is built through small, visible details. I look for clear explanations before sharing information, an obvious way to decline an optional step, and account controls that do not force me to search through unrelated screens. Cashli should be judged by those moments, not just by how attractive or simple the opening screen looks.
My advice is to pause whenever a prompt feels broader than the task requires. If the goal is to check eligibility, I would ask myself why a particular connection or permission is needed before accepting it. If there is a choice between using a bank connection and entering information manually, I would compare the explanations and choose the route I understand best. I would not assume that a familiar-looking finance screen is harmless simply because it uses friendly language.
There is also a practical trust check after registration: review the profile, notification, connected-account, and sign-in areas while the account is still new. Knowing where those controls live is easier before an urgent situation occurs. If I later decide that I no longer want to use the service, I want to know how to stop notifications, disconnect an account where that option is offered, and close or manage the profile without guessing.
Data-sensitive moments deserve extra attention
Cash-advance services naturally involve sensitive financial decisions. That means I would be particularly careful around identity details, income information, banking connections, transaction history, and any screen that discusses eligibility. I am not saying that every request is inappropriate; I am saying that the reason for each request should be understandable before I continue.
I would read the app’s privacy and data-use explanations rather than relying on the fact that it appears in a recognized app store. I would look for plain descriptions of what information is collected, why it is used, how long it may be retained, and whether it is shared with service providers or other parties. Those details are more useful to me than a general statement that the app takes privacy seriously.
Permissions are another place where I would stay deliberate. A finance app may need certain information to provide its service, but I would not grant access merely because the app asks. I would deny anything that seems unrelated to my intended use and then see whether the core service still works. If refusing a permission blocks the entire experience, that tells me something important about how dependent the app is on that access.
I would also avoid using Cashli on public Wi-Fi when entering financial details, and I would protect the account with a unique password if the app provides password-based access. After using it, I would sign out on a shared device and remove the app from any phone I no longer control. These are ordinary precautions, but they are especially worthwhile when an app is connected to money.
Account control matters more than a smooth sign-up
A polished application can still be frustrating if users cannot manage their own account. In my view, good user agency means being able to understand an offer before accepting it, decline optional data sharing, review connected information, adjust notifications, and find help when something goes wrong. I would look for those controls before requesting an advance, not after a problem appears.
One useful workflow is to separate exploration from commitment. I would first open the app, inspect the available explanations and settings, and note what information is requested. Only after deciding that the conditions fit my situation would I proceed with an application. This avoids making a rushed borrowing decision simply because the process has already taken several minutes.
I would also check the repayment details twice: once before submitting and again after confirmation. The second check is valuable because it lets me verify that the amount, schedule, and account destination match what I intended. I would save the confirmation inside my personal records, without storing sensitive credentials in a screenshot or an unsecured notes app.
If the app offers rewards, I would inspect the rules before spending time on them. The useful questions are whether an action is optional, what information it requires, whether there are restrictions, and how a reward is actually credited. I would never trade additional financial access for a small benefit unless the exchange is clear and worthwhile to me.
Where the app is stronger than familiar alternatives
Compared with asking a friend or family member, Cashli may offer a more structured process and a clearer digital record. Compared with a credit card cash advance, a dedicated cash-advance flow may feel less entangled with a revolving credit balance. Compared with visiting a bank, it is more convenient for someone who wants to handle an initial request from a phone.
Those comparisons are not automatic endorsements. A bank or credit union may be a better choice for a larger need, a longer repayment period, or a relationship where the terms are easier to understand. A credit card may be preferable for someone who already has a manageable purchase plan and knows the cost of using it. A small emergency fund is better than all of these options because it avoids a new obligation entirely.
Cashli’s main advantage is focus. It is built around a small, immediate financial need rather than trying to replace a checking account, investment platform, tax tool, or comprehensive budgeting system. That narrow purpose can make the decision easier, but it also means I would not expect it to organize my entire financial life.
Who should consider it, and who should skip it
I would consider Cashli if I had a one-off cash-flow problem, understood the repayment terms, and could cover the obligation from known income without sacrificing essentials. It may also suit someone who prefers a mobile application to a branch visit and is comfortable reviewing account and privacy prompts carefully.
I would skip it if I could not explain exactly how repayment would fit into my next budget. I would also avoid it if I was already using several advances, relying on borrowing for groceries or housing every pay cycle, or hoping the rewards would make an otherwise unsuitable loan worthwhile. In those cases, speaking with a nonprofit financial counselor, contacting a bill provider about a payment arrangement, or asking a trusted bank about alternatives may be more responsible.
People who are uncomfortable connecting financial accounts should not feel pressured to continue. If the app’s required process does not match my privacy boundaries, that is a valid reason to stop. Convenience is useful only when it remains consistent with the level of access I am willing to grant.
Small habits that make use safer
Before requesting anything, write down the exact amount needed and the date the money should be available. This prevents a vague emergency from becoming a larger request than necessary.
Compare the repayment obligation with the money left after rent, food, transport, utilities, and existing commitments. I would treat the advance as affordable only if those essentials remain protected.
Review every optional permission and notification setting during the first session. Turning off unnecessary alerts can make the app less intrusive and reduce the chance of responding impulsively to a promotional prompt.
Keep a personal note of the confirmed repayment details, but do not include passwords, security codes, or full account credentials in that note.
After the emergency passes, revisit the account controls and decide whether keeping the app installed still serves a purpose. Removing unused financial apps reduces clutter and limits unnecessary access on the phone.
My cautious verdict after reviewing the experience
Cashli: Cash Advance & Rewards is a focused finance app for people facing a small, short-term gap. Its free availability, Everyone age rating, and support for Android 8.0 or later make it approachable, while its audience of over 100 thousand installs shows that the concept has found users. Still, those points are secondary to the repayment terms and the information-sharing choices presented during use.
I like the idea of a direct mobile route for a limited emergency, but I would not describe the app as a universal answer to financial stress. The strongest use case is a single, clearly budgeted need with a realistic repayment plan. The weakest use case is ongoing dependence, where another advance only postpones the underlying problem.
My recommendation is to treat Cashli as a tool for a carefully measured situation, not as spare income. Read the offer before accepting it, question every sensitive permission, check the account controls, and keep the repayment date visible in your budget. If those conditions fit your circumstances, the app may be worth considering. If they do not, a slower but more transparent alternative is likely the better choice.
In the end, the most important feature is not the promise of quick access. It is whether I can make an informed choice, understand what I am agreeing to, and leave the service in control of my own account. That is the standard I would use before recommending Cashli to a friend.
FAQ
What is Cashli: Cash Advance & Rewards, and how does it work?
Cashli: Cash Advance & Rewards is a financial app designed to help eligible users access a cash advance and earn rewards through selected activities. After creating an account, you may be asked to provide personal and financial information so the service can assess eligibility. Available features, advance amounts, fees, repayment terms, and rewards can vary by user, location, and current offers, so review the in-app details carefully before accepting anything.
Is Cashli available to everyone, and what are the eligibility requirements?
Cashli is not necessarily available to every applicant. Eligibility may depend on factors such as your age, residence, income, employment or deposit history, identity verification, and other information requested during registration. Approval is not guaranteed, and meeting the basic requirements does not always mean an advance will be offered. Before downloading, confirm that the app operates in your country and read its current eligibility conditions.
How much does Cashli cost, and are there any hidden fees?
The total cost of using Cashli depends on the specific product and offer presented to you. Potential charges may include service fees, subscription costs, expedited transfer fees, or other applicable expenses. Do not assume that a cash advance is free simply because the app is free to download. Carefully check the disclosure screen, repayment amount, due date, recurring-payment terms, and cancellation instructions before confirming an advance or paid feature.
How are Cashli cash advances repaid, and what happens if I miss a payment?
Repayment arrangements can differ depending on the offer, your account, and the payment method you choose. The app should show the repayment date, total amount due, and any authorization required before you accept the advance. A missed or late payment may result in additional charges, unsuccessful withdrawal attempts, account restrictions, or other consequences described in the agreement. Make sure the repayment schedule fits your budget before proceeding.
Is Cashli safe to use, and what personal information does it collect?
Cashli may require sensitive information, including identity details, contact information, banking or payment data, and information used to determine eligibility. Before registering, review the app’s privacy policy, permissions, data-sharing practices, security explanations, and developer information in the official app store listing. Download only from an authorized source, use a strong password, and avoid sharing verification codes or account credentials with anyone claiming to represent the service.


